 (800) 728 8391

Updated on
100+ Key Real Estate Definitions and Terms (2026)
Real estate definitions form the foundation of an industry with its own language. From “addendum” to “zero lot line,” mastering the right real estate vocabulary helps you sound confident and avoid costly mistakes.
According to the NAR’s 2025 Member Profile, the typical agent completes 10 transactions per year. Every one of those deals involves contracts, disclosures, financing terms, and legal language. If you want to succeed in this industry, you need to speak it fluently.
This isn’t your typical real estate dictionary packed with dry textbook jargon. It’s a practical, plain-English guide built for agents and brokers who want to stay sharp and in control of every transaction. Once you get the hang of it, you’ll see how much smoother every deal becomes.
Let’s start with the basics.
What are the property types in real estate?
Real estate falls into five main property types: residential, commercial, industrial, land and special-purpose properties.
- Residential real estate: Used for living purposes. This includes single-family homes, condos, townhouses, duplexes, multifamily residences and luxury properties.
- Commercial real estate: Designed for business or income-generating purposes, such as office buildings, retail stores, shopping centers, hotels and medical facilities.
- Industrial real estate: Property used for manufacturing, production, storage, distribution, or research and development.
- Land: Refers to a defined parcel of land that may be undeveloped, vacant, agricultural, or prepared for future construction. This includes farms, ranches, timberland and buildable lots ready for development.
- Special-purpose real estate: Property built for a specific purpose, usually to serve the public or a community. Examples include schools, government buildings, libraries, parks and places of worship. These properties are not easy to convert to other uses without major changes.
In reality, most agents spend their time handling residential properties.
70%
of REALTORS® specialize in residential real estate, while only about 5% focus primarily on commercial properties.
Source: 2025 NAR Member Profile
Real estate terms to know in 2026
Below is a complete real estate glossary designed to simplify the language of the industry. These are the terms every agent should know heading into RE:
A
Absorption rate
Absorption rate measures how fast homes are selling in a market. It estimates how many months it would take to sell all active listings if no new homes came on the market. A healthy market usually sees a rate of five to seven months.
Acceleration clause
An acceleration clause lets a lender demand full loan repayment if the borrower breaks certain terms. It’s common in mortgage contracts and protects the lender from missed payments or early sales.
Addendum
An addendum is a contract addition or modification. All parties must sign it. Examples include lead paint disclosures or updates to repair agreements.
Adjustable-rate mortgage (ARM)
An ARM is a mortgage with a variable interest rate. Payments can rise or fall depending on market conditions. ARMs may save money initially, but rates can increase, so budgeting can be tricky. Fortune reports that 8% of mortgage holders choose ARMs, while 92% stick to fixed rates.
Adjustment date
The adjustment date is when an ARM’s interest rate changes. Most ARMs adjust annually, based on the loan’s terms. Buyers need to track this to anticipate payment changes.
Amenity
An amenity is a feature that enhances an investment property’s value or appeal. Examples include pools, gyms, covered parking, or laundry facilities.
Amortization
Amortization is a schedule showing loan repayment over time, usually monthly. It combines principal and interest payments, typically over 15 or 30 years.
Appraisal
An appraisal is a professional estimate of a subject property’s value. If the appraised value is lower than the offer, the buyer or seller may need to adjust the price, down payment, or loan terms.
Appreciation
Appreciation is an increase in property value over time. Factors include inflation, renovations, or neighborhood growth. It’s a key consideration for investors and homeowners.
Assessed value
Assessed value is the amount a local government assigns to a property for tax purposes. It’s based on square footage, condition, and comparable properties.
Assumable mortgage
An assumable mortgage allows a buyer to take over an existing loan. Most modern mortgages include a due-on-sale clause, making true assumptions rare.
B
Balloon mortgage
A balloon mortgage starts with smaller monthly payments and ends with a large final payment. It offers lower rates early but carries risk if the borrower cannot pay the balloon.
Bill of sale
A bill of sale documents the transfer of personal property. It lists the buyer, seller, sale price, and other key details. This protects both parties legally.
Biweekly mortgage
A biweekly mortgage requires payments every two weeks instead of monthly. This results in 26 payments annually (52 weeks), helping borrowers pay off loans faster and reduce interest.
Bridge loan
A bridge loan is a short-term loan used to cover costs between buying a new home and selling the current one. It helps buyers move quickly without waiting for a sale.
Built-ins
Built-ins are permanent fixtures like shelves, cabinets, or entertainment units. They can attract buyers if functional, appealing, and well-maintained.
Buydown
A buydown reduces a mortgage’s interest rate. Buyers or sellers pay upfront points or initial payments to lower monthly costs, often in exchange for a higher sale price. A discount point is a fee equal to 1% of your mortgage. For instance, on a $250,000 loan, one point would amount to $2,500.
C
Cash-out refinance
A cash-out refinance lets homeowners replace their current mortgage with a larger one. They can take the extra amount as cash. It’s a way to turn home equity into usable funds for upgrades, debt payoff, or investments. The trade-off? A higher rate or added fees.
Chain of title
The chain of title is the full record of all previous owners of a real property. It proves legal ownership and helps protect the buyer from future disputes. Title companies or attorneys verify this chain before closing through a detailed title search.
Clear title
A clear title means the property has no liens, claims, or legal disputes attached to it. It’s proof that real estate ownership can transfer without issues. When there are liens, it’s called a “cloudy” title—and clearing it can take time and legal work.
Closing
Closing is the final step in a real estate deal when ownership officially transfers from seller to buyer. It’s also when agents get paid. All parties agree on the date in advance and sign the purchase agreement.
Closing costs
Closing costs are the extra fees buyers and sellers pay at the end of a transaction. They typically total 3–5% of the sale price and include appraisals, property taxes, attorney fees, and title insurance. Always remind clients to verify wiring details—mistakes here can delay or derail a deal.
Commercial real estate
Commercial real estate is property used for business purposes. Examples include office buildings, factories, warehouses, shopping centers, and medical centers. Unlike residential real estate, commercial properties are supposed to generate income.
Commission
A commission is the fee agents earn for handling a real estate transaction. It’s usually about 6% of the sale price, paid by the seller. The buyer’s and seller’s agents, along with their brokers, split it. Be ready to explain how it’s shared, as clients often ask.
Community center
A community center is a building or space designed for public use within a neighborhood. It can host events, meetings, classes, and recreational activities. In the real estate industry, community centers add value to residential developments. They offer shared amenities that attract buyers and support a sense of neighborhood.
Comparable properties (comps)
Comparable properties, or “comps,” are recent real estate sales in the same area with similar size, condition, and features. Agents use them to help sellers set realistic prices and buyers make smart offers. Comps are the backbone of any solid pricing strategy.
Comparative market analysis (CMA)
A comparative market analysis is a detailed report that estimates a property’s market value. It uses comps, sale history, and neighborhood trends. It’s how agents show expertise, build trust, and back up pricing recommendations with data.
Construction loan
A construction loan is short-term financing used to build a property. Borrowers use it to pay for materials and labor until they secure long-term financing. It’s riskier for lenders, so interest rates are higher and approval is stricter.
Contingency
A contingency is a condition that you have to meet before closing a sale. Common examples include home inspections, financing approval, or selling the buyer’s current home. Once the parties clear all contingencies, they can move the deal forward.
Conventional mortgage
A conventional mortgage is a home loan that’s not backed by the government. Borrowers typically have stronger credit, higher down payments, and may avoid mortgage insurance. It’s the most common loan type for qualified buyers.
Convertible adjustable-rate mortgage (convertible ARM)
A convertible ARM starts like a regular adjustable-rate mortgage with a lower initial rate that adjusts over time. The difference? Borrowers can later switch to a fixed-rate loan. It’s a flexible option for buyers betting on stable or falling interest rates.
D
Days on market (DOM)
Days on market measures how long a property stays active before going under contract. It starts the day you list it on the MLS and ends when the seller accepts an offer. A high DOM can signal overpricing or low demand. In May 2025, homes spent a median of 51 days on the market, according to Realtor.com data.
Deed
A deed is the legal document that moves property ownership from seller to buyer. It’s recorded at the county clerk’s office and serves as proof of who officially owns the home. Simple, but powerful—no deed, no ownership.
Delinquency
Delinquency happens when a borrower misses mortgage payments for a specified period. At that point, the lender may start foreclosure proceedings. It’s a warning sign that the loan is at risk, and timing is critical to avoid bigger trouble.
Depreciation
Depreciation is a drop in a property’s value over time. It can happen because of market downturns, neighborhood decline, or poor property condition. While some factors are out of the owner’s control, smart upgrades and maintenance can help slow the slide.
Debt coverage ratio (DCR)
The debt coverage ratio is one of the most important real estate metrics. It measures whether a property’s net operating income is enough to cover its debt payments. You calculate it by dividing NOI by total annual debt service. A ratio above 1 means the property generates enough income to pay its loan obligations.
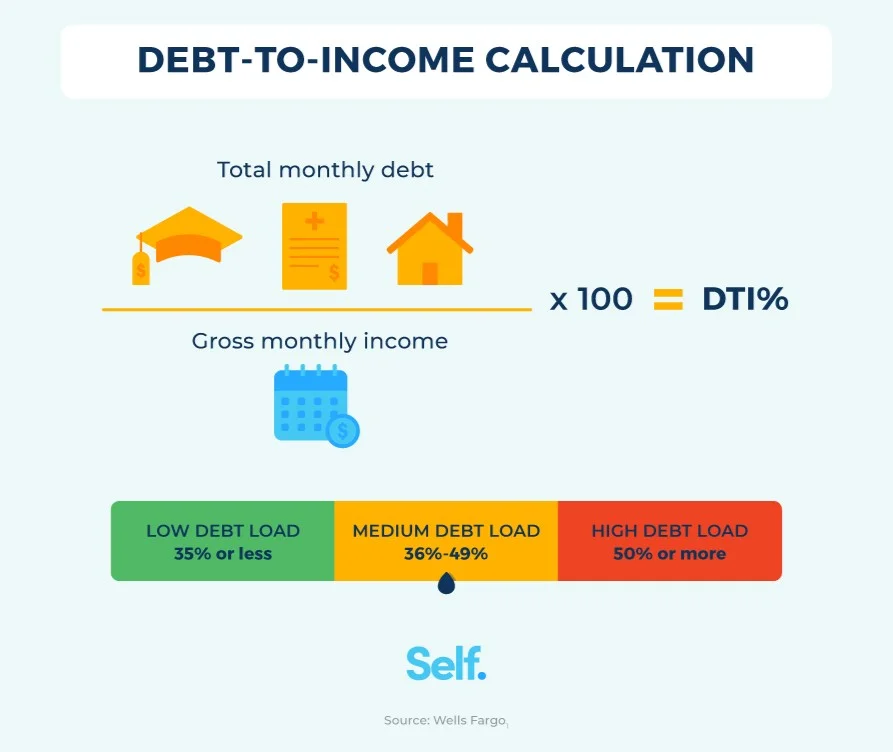
Debt-to-income ratio (DTI)
The debt-to-income ratio compares a borrower’s total monthly debts to their gross monthly income. Lenders use it to judge if the buyer can handle a mortgage. To find it, divide monthly debt payments by gross income—the lower the ratio, the better the odds of approval.
Disclosure
Disclosure means being upfront about a property’s known issues. Sellers must legally share defects like leaks, foundation problems, or mold. Full transparency builds trust and protects everyone from legal headaches.
Down payment
A down payment is the cash a buyer pays upfront toward a home’s purchase price. Conventional loans often require 20%, but some government-backed programs need far less. Buyers who put down less than 20% usually pay private mortgage insurance (PMI) until they build enough equity.
Due-on-sale clause
A due-on-sale clause makes the borrower repay the full loan when selling the property. It protects lenders by stopping new owners from taking over the loan without approval.
E
Earnest money deposit
An earnest money deposit is also called a good faith deposit. It’s the money a buyer puts in escrow to show they’re serious about buying a property. It’s usually 1–3% of the purchase price and goes toward the down payment or closing costs. If the deal falls through, the seller may keep some or all of it depending on the terms.
Economic obsolescence
Economic obsolescence means a property loses value because of outside factors the owner can’t control. It happens when the area declines—for example, due to local job loss, nearby factories, or stalled development. It’s about the neighborhood, not the home itself.
Eminent domain
Eminent domain gives the government the right to take private property for public use, such as building roads or schools. The owner receives fair compensation for the real estate. It’s legal, but rarely popular.
Encroachment
Encroachment happens when someone builds on land that belongs to someone else without permission. A common example is a fence, driveway, or shed that crosses the property line. It can lead to boundary disputes or legal action if not resolved.
Encumbrance
An encumbrance is any claim or restriction on a property that affects ownership or transfer. Examples include liens, mortgages, or easements. It doesn’t always stop a sale, but you must resolve it before closing.
Equal Credit Opportunity Act (ECOA)
The Equal Credit Opportunity Act (ECOA) stops lenders from discriminating against borrowers. It covers reasons like race, color, religion, national origin, sex, marital status, age, or use of public assistance. By banning these practices, the law ensures everyone has fair access to credit.
Equity
Equity is the part of a property that owner truly owns. It’s the difference between the home’s market value and the amount still owed on the mortgage. Equity grows as the buyer pays the loan down or the property appreciates in value. As of the second quarter of 2025, U.S. households held approximately $35.8 trillion in equity in real estate, according to FRED.
Escrow
Escrow happens when a neutral third party holds funds or documents during a real estate deal until the parties meet all conditions. Most often, it involves an escrow agent holding the buyer’s earnest money until closing. It keeps everyone honest and protected.
Extension
An extension gives buyers extra time to complete a real estate agreement. They often request it for financing or inspections. Sellers decide whether to approve or deny it based on their priorities and the deal’s progress.
F
Fair Credit Reporting Act (FCRA)
The Fair Credit Reporting Act is a U.S. law that protects your personal and financial information. Passed in 1970, it makes credit agencies keep your data fair, accurate, and private. It also lets you see your credit report and dispute any errors.
Fair market value
Fair market value is the price a property would sell for in an open and competitive market. It’s the number both a willing buyer and seller can agree on—without pressure or special conditions. Don’t confuse it with appraised or assessed value—they’re not the same thing.
Federal Home Loan Mortgage Corporation (Freddie Mac)
The Federal Home Loan Mortgage Corporation, commonly known as Freddie Mac, is a government-sponsored enterprise that buys mortgage loans from lenders. By purchasing these loans and selling them to investors, Freddie Mac helps keep money flowing in the housing market and supports stable mortgage rates.
Federal National Mortgage Association (Fannie Mae)
The Federal National Mortgage Association, commonly known as Fannie Mae, is a government-sponsored enterprise that buys mortgage loans from lenders. By purchasing these loans and selling them to investors, Fannie Mae helps keep money flowing in the housing market and supports stable mortgage rates.
FHA mortgage
An FHA mortgage is a government-backed loan insured by the Federal Housing Administration. It allows lower credit scores and smaller down payments, making it a go-to option for first-time buyers. The trade-off is paying mortgage insurance premiums for extra protection.
Fixed-rate mortgage
A fixed-rate mortgage keeps the same interest rate for the entire life of the loan—usually 15 or 30 years. It gives borrowers predictable monthly payments and peace of mind. If rates drop, refinancing is an option, but it comes with closing costs.
For sale by owner (FSBO)
“For sale by owner,” or FSBO, means a homeowner is selling without using a licensed agent. Most do it to avoid paying commission, but they often end up with fewer offers and lower sale prices. A quick call to an agent can usually fix that mistake. According to NAR, only 6% of home sales in 2024 were FSBO—the lowest share ever recorded.
Functional obsolescence
Functional obsolescence means a home loses value due to design or structural issues. It can be low ceilings, a bad layout, or an old roof. Even over-improving can hurt value—like combining two bedrooms into one big suite.
G
Good-Faith Estimate (GFE)
A Good-Faith Estimate is a document that outlines the estimated costs of getting a mortgage. Lenders must provide it to show borrowers what they’ll likely pay for things like title fees, escrow, and closing costs. Today, it’s mostly replaced by the Loan Estimate and Closing Disclosure forms. It helps buyers compare lenders and avoid surprise fees before signing.
Grantee and grantor
A grantor is the person selling or transferring property. A grantee is the person receiving it. The grantor signs a deed to legally transfer ownership to the grantee. The type of deed—and the rights it conveys—can vary by state. That’s why having a real estate attorney review the details of any deed transfer is always a smart move.
H
Home inspection
A home inspection is a professional check of a property’s condition. The buyer usually orders it after the seller accepts the offer. Inspectors check the structure, roof, foundation, plumbing, electrical, and HVAC systems. Their report helps buyers spot hidden issues and negotiate repairs before closing.
Home warranty
A home warranty covers the repair or replacement of major systems and appliances. It protects things like plumbing, heating, or kitchen equipment. It’s different from homeowner insurance—it handles wear and tear, not disasters. Buyers often appreciate the peace of mind it offers, and sellers use it to make listings more appealing.
Homeowner’s Association (HOA)
A Homeowner’s Association manages shared spaces and enforces rules within a community or condo complex. It collects monthly or annual fees to maintain common areas and preserve property values. Failing to pay can lead to fines or even a lien on the property. Always make sure buyers understand the costs and rules before committing.
Homeowners insurance
Homeowners insurance protects the property and the lender against damage, disasters, or accidents. It typically covers the home’s structure, personal belongings, and liability for injuries on the property. Premiums are often included in the mortgage payment. Some regions, like flood or hurricane zones, may need extra coverage.
I
Incentive
An incentive is anything advertised or offered by a brokerage to attract clients or generate business. It may include a promise, gift, service, discount, contest or other item of value. Incentives can typically be offered only by the brokerage itself, not by an individual real estate professional, depending on state regulations.
Internet Data Exchange (IDX)
Internet Data Exchange (IDX) allows agents to show MLS listings on their websites. It updates property data automatically and lets you choose which listings to feature. With IDX, your site can highlight the homes your clients want and generate leads in real time.
Judicial foreclosure
Judicial foreclosure happens when a borrower defaults on a mortgage. The lender must use the court system to take back the property. The court reviews the case, issues a ruling, and only then can the foreclosure move forward. This adds time but ensures the process follows legal protocols. In 2024, 322,103 U.S. properties faced foreclosure filings. That’s only 0.23% of all housing units, according to ATTOM’s report.
Jumbo loan
A jumbo loan covers mortgages above standard limits. Lenders offer it without government backing. They require higher credit scores, bigger down payments, and stronger income. Buyers usually use it for luxury homes or expensive markets.
L
Land contract
A land contract is a seller-financed deal where the buyer makes payments directly to the owner. The seller keeps legal title until the buyer pays in full.
Legal description
A legal description precisely identifies a property using boundaries, measurements, or survey references. Brokers and title insurance companies use it to avoid confusion over ownership.
Legal title
A legal title gives a person the legal right to own, use, and transfer real property. It proves who holds ownership and what rights come with it. Unlike a deed, a title reflects your legal claim to the property, not the document itself.
Lessee and lessor
A lessor is the property owner who rents out units. A lessee is the tenant who pays to use the property. Owners of large buildings often hire leasing agents to fill units. Smaller landlords usually manage leases on their own. According to data from iPropertyManagement.com, private individuals own 68.7% of rental properties in the U.S.
Lien
A lien is a legal claim against a property for unpaid debt. Owners agree to voluntary liens, like a mortgage. Construction or tax liens, which the law can impose, can block a sale until someone pays them. Explaining liens helps clients avoid surprise roadblocks.
Life cap
A life cap limits how much the interest rate can change on an adjustable-rate mortgage over the life of the loan. Even if market rates spike, the borrower won’t exceed this cap. It protects clients from runaway payments and gives them predictability.
Loan commitment
A loan commitment is a lender’s formal promise to fund a mortgage. It confirms the loan amount, interest rate, and terms, giving buyers confidence to move forward.
Loan officer
A loan officer is a licensed professional who guides borrowers through the mortgage process. This person helps choose the right loan, submits applications, and answers client questions. The officer is your go-to for all financing details.
Loan origination
Loan origination is the process of evaluating a borrower’s loan application. It often includes a fee for processing, assessing credit risk, and collecting documentation. This step sets the stage for approval.
Loan servicing
Loan servicing handles everything after a mortgage closes. It tracks payments, manages escrow accounts, sends statements, and follows up on delinquencies. Clients may pay a different company than the one that issued the loan.
Loan-to-value (LTV)
Loan-to-value is the ratio of a loan amount to the property’s value. Divide the loan by the property price to calculate it. Higher LTVs mean more risk for lenders. They can also affect interest rates and mortgage insurance requirements.
Loss mitigation
Loss mitigation helps homeowners avoid foreclosure when they fall behind on payments. Specialists work with lenders to create modified repayment plans, sometimes requiring asset liquidation. It’s a tool to keep clients in their homes and protect lenders’ real estate investments.
M
Mentor
A mentor is an experienced real estate professional who guides newer agents through transactions, contracts, negotiations, and business development. Many brokerages offer mentorship programs to help agents build skills, confidence, and compliance knowledge early in their careers.
Mortgage
A mortgage, also called a mortgage loan, is financing used to purchase real property when the buyer cannot pay the full price upfront. The property serves as collateral for the lender. Borrowers repay it over time with interest.
Mortgage broker
A mortgage broker checks various lenders to find the best loan terms for a borrower. It saves clients time and helps secure competitive interest rates and fees.
Mortgage rate lock
A mortgage rate lock secures an interest rate during loan processing. It protects the borrower from rising rates before closing and can reduce fees. Rate locks give buyers confidence and cost certainty.
Multi-unit building
A multi-unit building contains two or more separate residences that share common access.
Multiple listing service (MLS)
The MLS is a database of homes for sale used by real estate agents. It provides detailed property info, price history, and photos. With almost 600 MLSs in the U.S., agents can access local listings, market trends, and integrate them into websites to attract clients.
>> Also check: How to Get MLS Listings on Your Website in 7 Steps? + Tips
N
National Association of REALTORS® (NAR)
The NAR is America’s largest real estate trade association. Founded in 1908, it offers education, certifications, and resources to over 1.4 million members. Joining NAR and your local association boosts credibility and professional expertise.
Negative amortization
Negative amortization happens when a borrower pays less than the interest owed on a loan. The unpaid interest adds to the principal, increasing the total debt over time.
Net Operating Income (NOI)
Net Operating Income is a property’s income minus operating expenses. It shows how much the property earns from its core operations.
No-cash-out refinance
A no-cash-out refinance replaces an existing mortgage without taking extra money from the home’s equity. Borrowers often do this to secure a lower interest rate or shorten the loan term.
No-cost mortgage
A no-cost mortgage pays all closing costs upfront by adding a slightly higher interest rate. It works best for buyers who plan to stay a few years, saving money at closing.
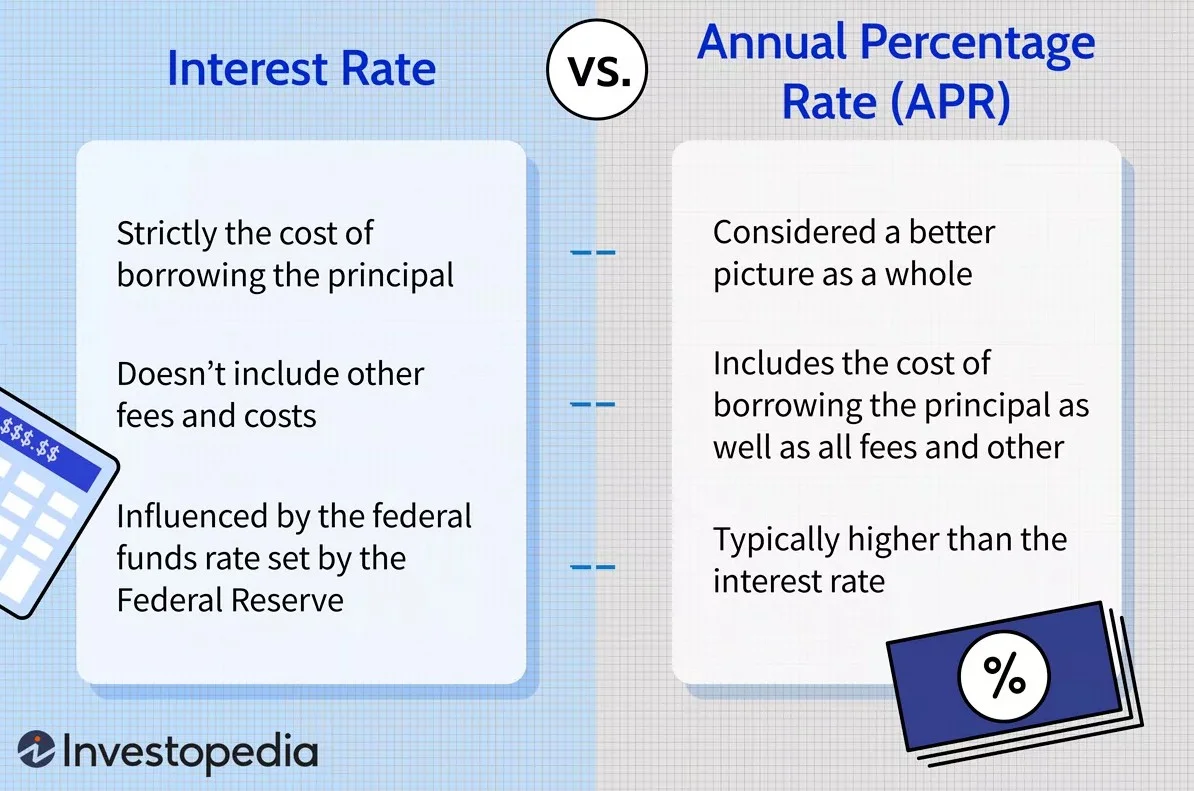
Note rate
The note rate is the interest rate used to calculate a loan’s monthly payment. It’s different from the APR, which includes fees and extra costs for comparing loans.
Open listing
An open listing is a non-exclusive agreement where any agent can find a buyer and earn the commission. Sellers might save money, but they lose guidance and marketing motivation from agents.
Original principal balance
The original principal balance is the total loan amount before any payments. It shows clients what they owe at the start, excluding escrow or fees.
Origination fee
An origination fee goes to the lender for processing a mortgage. Usually, it is 0,5–1,5% of the loan. It could be around $2,500 on a $200,000 mortgage, so clients should factor it into their upfront costs.
Owner financing
Owner financing happens when the seller acts as the lender. Buyers can bypass strict bank rules, while sellers set terms and often close faster. Both parties should understand the risks and legal protections involved.
P
Pay-at-closing leads
Pay-at-closing leads let you work buyer or seller leads without upfront costs. You only pay once a deal closes, but the fee can be steep—sometimes up to 35% of your commission.
Pending
A pending sale occurs when the buyer meets all contingencies and the deal moves toward closing. The sale will likely proceed, but the buyer risks losing earnest money if it fails.
Per diem fees
Per diem fees are daily charges for delayed loan closings. Calculate by multiplying the loan amount by the interest rate, then dividing by 365. Sellers can also use per diem clauses to cover extra costs if buyers miss closing deadlines.
Personal property
Personal property includes movable items that are not permanently attached to the home, such as furniture, appliances not built in or décor. In a real estate transaction, personal property must be listed separately if included in the sale.
Principal, interest, taxes & insurance (PITI)
PITI adds up a borrower’s monthly principal, interest, taxes, and insurance. It’s the total monthly housing cost. Keep PITI under 28% of a client’s monthly income to help them stay comfortably within budget.
Planned unit development (PUD)
A PUD is a group of homes, such as townhouses, condos, or single-family houses. It offers shared amenities like pools, parks, and parking. HOAs manage their rules and fees.
Pocket listing
A pocket listing is an offer marketed quietly outside the MLS. Sellers use it for privacy or to test the market. Agents must follow NAR’s Clear Cooperation Policy. This rule requires listing the property publicly within a day of any marketing.
Pre-approval
Pre-approval confirms a buyer’s eligibility for a loan based on verified financial info. It’s stronger than prequalification but does not guarantee final mortgage acceptance. Pre-approval letters give sellers confidence in an offer.
Predictive analytics
Predictive analytics uses data to forecast market activity. It analyzes demographics, property trends, and behavior to make predictions. Agents can target marketing and generate leads by anticipating who is likely to buy or sell next.
Private mortgage insurance (PMI)
PMI protects lenders if a borrower defaults on a loan with a down payment under 20%. Borrowers pay a monthly premium until they build enough equity to cancel it.
Promissory note
A promissory note is an express and absolute promise by the borrower to repay a mortgage in full. It accompanies the loan contract. Once the borrower pays the debt, the lender returns the mortgage note. It’s one of the happiest moments in homeownership.
Prequalification
Prequalification is the first step in getting a mortgage. The lender estimates how much a borrower might qualify for based on basic financial info. It’s not a guarantee and is less thorough than pre-approval.
Prime interest rate
The prime interest rate is the base rate banks use to set mortgage, credit line, and credit card rates. Each bank sets its own prime rate based on the federal funds rate set by the Federal Reserve Bank. It currently stands at 7.25%. Clients with strong credit, high down payments, and low DTI can negotiate better rates.
Principal
Principal is the amount of money a borrower must repay on a loan, excluding interest. In real estate, it sometimes means the buyer or seller who authorizes an agent. It can also refer to the managing broker who oversees transactions.
Probate
Probate is the legal process of reviewing a deceased person’s estate and transferring property. It happens whether or not there is a will.
Property landing page
A property landing page is a dedicated webpage created to promote a specific listing. It typically includes photos, pricing, property details, neighborhood information and lead capture forms. Agents use property landing pages, connected to their real estate website, to generate buyer inquiries and track online marketing performance.
Proof of funds
Proof of funds shows a buyer has the cash needed to purchase a property. It’s required for all-cash offers and must cover the full sale price, down payment, and closing costs. Funds have to be liquid, not tied up in stocks or bonds, and the letter usually comes from a bank.
Q
Quit-claim deed
A quit-claim deed transfers property ownership without a sale. No money changes hands, and the grantor makes no guarantees about the title. Families often use it to transfer homes between relatives.
R
Real estate agent
A real estate agent holds a state license to help clients and customers buy, sell, or rent property. This professional follows legal rules and, if part of NAR, follows a strict code of ethics.
Because licensing is regulated at the state level, agents who want to work across state lines must understand license reciprocity and portability rules, which determine whether they can legally conduct transactions in another state.
Real estate broker
A broker holds a higher-level license than an agent. Brokers can work independently, run a brokerage, and supervise agents. Agents usually work under a broker and can’t operate their own firm without one.
Real estate development
Real estate development covers improving land or buildings for sale or lease. It includes renovating existing structures, buying raw land, and preparing properties for new use or resale.
Real-estate owned (REO)
REO properties are real estate that a bank owns after foreclosure or a failed short sale. Lenders take possession when borrowers default, often to resell the property.
Real Estate Settlement Procedures Act (RESPA)
RESPA protects buyers by requiring lenders to disclose costs and schedules in a transaction. It bans kickbacks and inflated fees, ensuring proper handling of escrow funds.
Real property
Real property refers to land and anything permanently attached to it, such as buildings, fences, or fixtures. Unlike personal property, it cannot be moved without altering or damaging the structure. In real estate transactions, contracts typically transfer real property unless stated otherwise.
REALTOR
A REALTOR is a licensed agent who pays dues to NAR and follows a strict code of ethics. Remember: all REALTORS are agents, but not all agents are REALTORS. According to NAR, 65% of all REALTORS are female, and the median age of REALTORS is 55.
>> Further reading: Real Estate Agent vs. Realtor: 7 Key Differences Compared
Refinance
Refinancing means taking a new loan on the same property. It can lower interest rates, reduce monthly payments, or shorten the loan term.
Residential real estate
Residential real estate is property used for living purposes. This includes single-family homes, condos, and apartments. It’s different from commercial real estate, which is for business use.
Right of first refusal (ROFR)
ROFR gives a potential buyer the chance to make an offer before anyone else. The seller sets the price, and the buyer can match it. It doesn’t guarantee the sale, but it provides a competitive edge.
S
Sales contract
A sales contract is a legal document that sets the terms of a property sale. It shows the price, closing date, contingencies, and each party’s responsibilities. The sale agreement protects both sides and makes expectations clear before closing.
Sale-leaseback
A sale-leaseback happens when a property owner sells a real estate and then leases it back from the buyer. This lets sellers free up cash while staying put for a set period. It can be a strong negotiating tool in deals where timing or cash flow is tight.
Secondary mortgage market
The secondary mortgage market is where lenders sell existing home loans to investors. This frees up cash so lenders can offer more mortgages. Banks, agencies, and pension funds buy these loans, often packaged as mortgage-backed securities. It keeps money moving in the housing market and helps more buyers get financed.
Secured loan
A secured loan uses an asset as collateral to guarantee repayment. Mortgages are the most common type, using the property itself. Other examples include car loans or equipment financing. Lenders face less risk, which often translates to lower interest rates for borrowers.
Short sale
A short sale occurs when a lender allows a homeowner to sell a property for less than the remaining mortgage balance. Buyers can get a bargain, but the process is complex and slow. Sellers and agents must navigate lender approvals, various offers, and paperwork carefully.
Staging
Staging prepares a home for sale by arranging furniture, décor, and styling to highlight its best features. It helps buyers imagine living there and can increase the final sale price. Even small improvements, like decluttering or fresh paint, can make a big difference. According to NAR, 29% of agents reported that staging increased home value by 1–10%. 49% of them sold their homes faster.
Surveyor
A surveyor measures and maps property boundaries and land features. These reports provide both parties with precise square footage, easements, and potential issues. Accurate surveys prevent disputes and ensure clean titles during transactions.
Sweat equity
Sweat equity is the value added to a property through the owner’s labor rather than money. Fixing, renovating, or upgrading a home yourself increases its market value. Agents can leverage this when advising investors or sellers looking to boost resale profits.
T
Tax deductions
Agent tax deductions are business expenses that licensed real estate professionals may deduct to reduce taxable income.
Tenancy
Tenancy refers to the legal arrangement in which one party occupies or owns real property. In ownership structures like joint tenancy or tenancy in common, each owner holds an undivided interest in the property. This means no single owner controls a specific physical portion of the property unless formally divided.
Title insurance
Title insurance protects owners and lenders from unexpected claims on a property. If someone asserts ownership or a lien after closing, it covers legal and financial risks. A title insurance policy provides the specific terms and coverage limits for both parties.
Title search
A title search examines public records to ensure a property’s title is clear of liens or disputes. Most buyers hire a title company or attorney to do this. Doing it yourself is possible, but risky, especially for older properties.
Transfer of ownership
Transfer of ownership is the legal process of moving the title and deed from seller to buyer. It happens at closing and finalizes the transaction.
Transfer tax
A transfer tax is a government fee applied when a property changes ownership. It’s usually a percentage of the sale price or a set amount, paid by the seller.
Truth in Lending Act (TILA)
TILA ensures borrowers get clear, standardized information about loan costs. This lets buyers compare mortgages and choose the best option without hidden fees or surprises.
Turn-key
A turn-key property is ready to move in with no repairs or upgrades needed. Buyers can settle in immediately. For agents, turn-key listings often sell faster and with fewer negotiations.
U
Under contract
A property is under contract when the buyer and seller agree on price and terms and sign a contract. Contingencies still apply, and the sale hasn’t closed yet. Once the parties meet all conditions, it moves to pending.
Upside-down mortgage
An upside-down mortgage, sometimes called an underwater mortgage, occurs when the homeowner owes more than the property’s current value. During the 2008 financial crisis, 29,1% of U.S. homeowners owed more than their homes were worth. According to Zillow, home values dropped about 10%, fueling the “upside-down mortgage” problem.
USDA loan
A USDA loan gets backing from the U.S. Department of Agriculture. It offers no down payment and lower mortgage insurance costs. Properties must be in rural or suburban areas to qualify.
V
Veterans Affairs (VA) mortgage
A VA mortgage comes with a guarantee from the Department of Veterans Affairs. It helps veterans, active-duty service members, and surviving spouses get favorable terms. Many loans require no down payment or mortgage insurance.
Variance
A variance is a special exception to zoning laws. It lets an owner make changes or use the property in a way not allowed by local rules.
W
Walkthrough
A walkthrough is the final inspection before closing. Buyers check the property’s condition to confirm repairs, appliances, and agreed-upon items meet the contract. They should immediately report any issues.
Withdrawn listing
A withdrawn listing is a home that the seller pulls off the market while continuing to work with the agent. It differs from an expired listing, which ends the agent’s representation.
Z
Zero lot line
A zero-lot-line home is built right up to the property boundary. It usually shares walls or fences with neighboring properties.
Zoning ordinance
A zoning ordinance is a local law that tells property owners how they may use their land. It divides areas into residential, commercial, or industrial zones.
Real estate meaning: a quick summary of essential terms
Now you’ve got the language of real estate down—the words that shape every offer, listing, and closing. You might even find them handy when updating listings on your Placester website. After all, every great deal starts with the right communication.
Keep exploring, because the market never stops evolving, and neither should your vocabulary. The more fluent you become, the more doors open—literally and professionally.
Published on

Take your real estate website to the next level with Placester!
Discover new opportunities and save thousands of dollars every year.