 (800) 728 8391

Updated on
Comparative Market Analysis in Real Estate: Guide + 6 Tips for Agents
Quick summary:
- 🏠 CMA is a pricing guide, not an appraisal. It reflects current market behavior and supports pricing decisions, but it doesn’t replace a formal valuation.
- 📊 CMA works when key elements align. Reliable comps, active listings, smart adjustments, and market context define a realistic value range.
- ⚙️ CMA follows a repeatable process. Clear goals, solid data, and the right tools help turn raw numbers into a client-ready report.
A Comparative Market Analysis (CMA) is a useful tool that real estate pros use to value a property. It helps you price a listing smartly or make an offer that stands a real chance of getting accepted.
Here’s why CMA matters today:
4.35M
The U.S. existing home market ran at about 4.35 million sales a year in December 2025.
Source: tradingeconomics.com
In a market this active, pricing a property right from the start makes the difference between a smooth sale and a listing that stalls. That’s why you should stick with this guide and learn how to build a CMA and use it to your advantage.
What is a comparative market analysis in real estate?
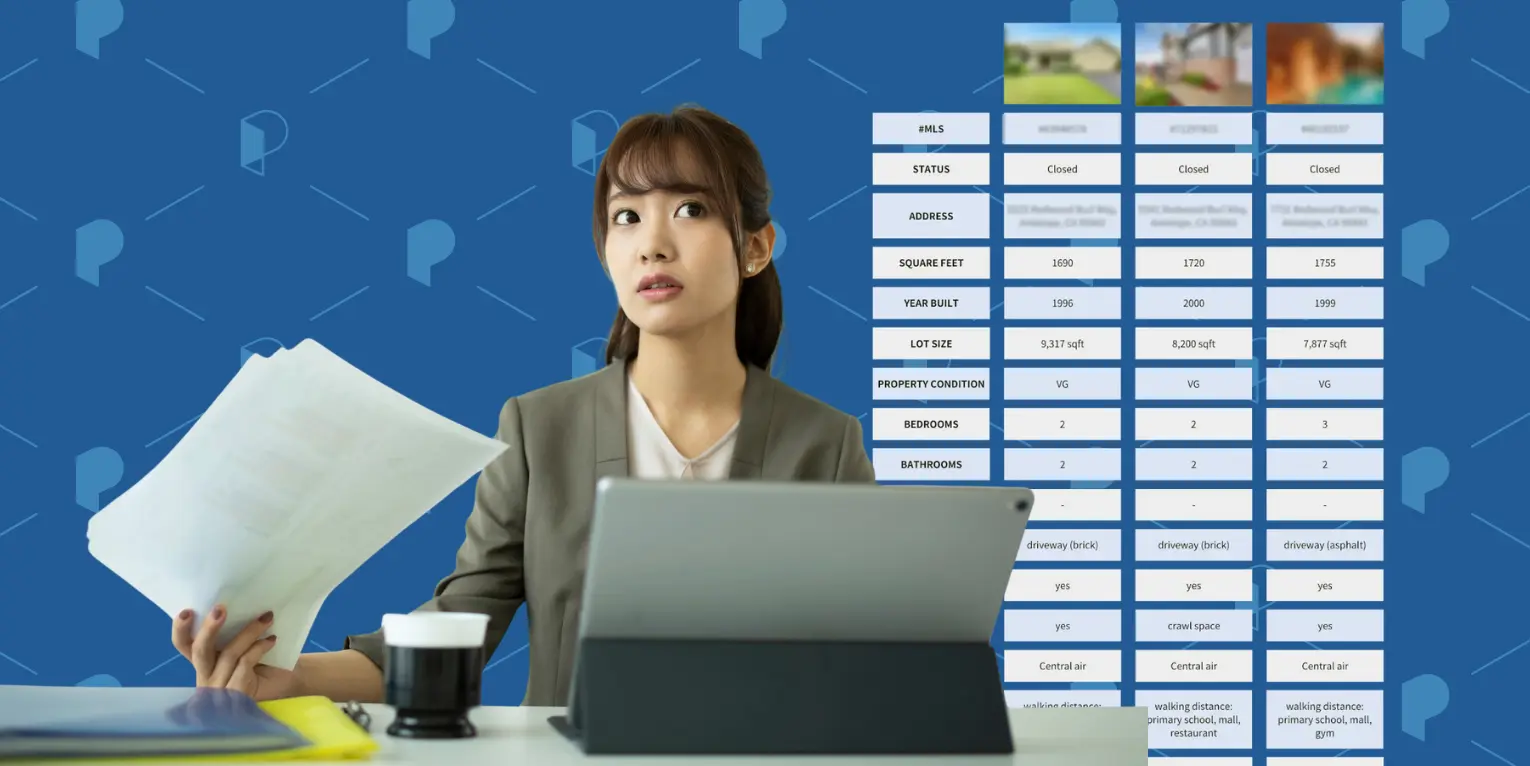
A comparative market analysis is a data-driven snapshot of what similar homes in a neighborhood are selling for right now. The comparison focuses on factors that move the price:
- Size
- Age
- Condition
- Location
- Upgrades
- Access to local amenities
These similar homes are called comparables, or “comps,” and they form the backbone of the analysis.
An agent pulls this data together to read the market as it stands today. A solid CMA usually includes photos, charts, and clear breakdowns that show how each comp stacks up. The result is a realistic price range, not a single fixed number. Think of it as informed judgment backed by real sales, where experience matters just as much as the data itself.
👉 Not just CMA—explore other real estate definitions and terms.
Why do both buyers and sellers need a CMA?
A CMA lets sellers price smart and helps buyers avoid overpaying.
- For sellers, a CMA helps set a price that matches real demand. That prevents pricing too high or too low. The home stays competitive and sells closer to its true value.
- For buyers, a CMA shows whether a listing price makes sense based on recent local sales. With real data, they can make confident decisions instead of relying on emotion or guesswork.
62%
In 2025, about 62% of homebuyers paid less than the original list price, the highest level since 2019.
Source: The Wall Street Journal
With an average discount of around 8%, a CMA gives buyers real leverage by showing where there’s room to negotiate and avoid overpaying.
Both sides also gain insight into current market trends. Clear signals on prices, supply, and demand make negotiations smoother and reduce surprises during the deal.
What elements make up a CMA report?
A solid CMA report includes a subject property overview, active listings, sold homes, and a clear price recommendation. Below, you’ll find a list of the key elements that make an analysis useful and reliable:
🔑 Subject property overview
The first part describes the home and sets the baseline for the entire CMA. It captures the facts that directly influence value, such as:
- Location and address
- Property type
- Total square footage
- Lot size
- Year of construction
- Number of bedrooms and bathrooms
- Parking and garage capacity
The same principles that make a listing description compelling apply to how you frame and present your comps.
⚖️ Comparable sales (“comps”)
Comparable properties are the backbone of a CMA because they show how much buyers paid for similar homes in the area. These are real listings from the same neighborhood, not estimates or averages pulled from a wide map.
A strong CMA focuses on recently sold homes. Most reports rely on three to five comparable properties sold within the last three to six months and located close to the subject property. The exact range depends on the local market and available data. The closer the match, the more reliable the comparison.
Expired or withdrawn listings add extra context. They show which homes failed to sell and often reveal where pricing missed the mark. This helps define not just what works, but also what the market rejected.
👉 Learn how to find off-market properties.
🏷️ Active listings
Active listings show what a property is competing with right now. They reflect seller expectations, not final sale prices, but they still matter.
This part helps set realistic boundaries. It includes price ranges that buyers see online and compare side by side. If similar homes sit unsold at a certain price, that’s a signal worth noticing.
While these listings don’t confirm value on their own, they add real-time context. They explain market pressure, buyer options, and how aggressive or conservative a price should be right now.
Tracking active competition is easier when your CRM flags new listings in your farm area automatically.
🛠️ Adjustment data
Adjustments account for the real differences between the subject property and the comps. No two homes are identical, so prices need correction to stay fair.
The real estate agent starts with the sale price of each comp and then adjusts up or down. Comparison is usually based on three factors:
1. Interior features
Adjustments start with what’s inside the home. More square footage usually increases value. Fewer bedrooms often reduce it. A renovated kitchen, a newer roof, or an added bathroom can push the price higher. Visible wear, outdated systems, or needed repairs pull it down.
2. Surrounding area
Location details shape value just as strongly as the interior. Street quality, traffic, noise, and privacy all matter. Nearby schools, shops, parks, and public transit can raise demand. Two homes with the same layout can be priced very differently based on what sits outside the front door.
3. Current market conditions
Timing affects every comparison. A home sold three months ago may need adjustment if demand shifted or inventory changed. Rising prices, slower sales, or tighter supply all influence value. This step keeps the CMA tied to today’s market, not outdated numbers.
📈 Market analysis
Earlier adjustments reflect how market changes affect individual comps. Market condition analysis zooms out and looks at the bigger picture.
This section explains what is happening across the local market as a whole. It examines supply, demand, and how quickly homes move from listing to closing. These signals show whether prices have room to grow or face resistance.
Key indicators include:
- Inventory levels
- Average days on market
- And the recent price direction
Low supply and short selling times point to a seller-leaning market. Higher inventory and slower sales shift leverage toward buyers.
Market condition analysis also reveals momentum. Are prices climbing, leveling off, or starting to soften? That context helps set expectations before pricing or negotiating.
This part of the CMA doesn’t adjust numbers. It explains the environment those numbers live in and helps you choose the right strategy for current conditions.
👉 Learn the key real estate metrics every agent should follow.
💰 Estimated value of a property
In this part, the real estate agent estimates a home’s value and recommends its price. This is the final takeaway of the CMA.
The report suggests the property’s value by comparing recent sales and narrowing the numbers into a clear price range. That range reflects what buyers have proven they will pay.
Note that the result is not a single magic number. It’s a window of value that accounts for market behavior, competition, and buyer demand. A tight range signals a stable market. A wider one suggests uncertainty or fast-moving conditions.

How does a CMA compare to professional real estate appraisal?
The key difference between a CMA and a professional appraisal comes down to purpose, formality, and who uses the result. Both of them estimate property value, but they serve different roles and appear at different stages of a deal.
A CMA reflects how the market is behaving right now. A real estate professional builds it from recent local sales and current competition to guide pricing or offer strategy. It’s practical, fast, and rooted in actual buyer behavior. Think of it as a market-driven price reality check.
An appraisal is more formal and more rigid. A licensed appraiser prepares it, following strict standards and often inspecting the property. Lenders rely on appraisals to confirm that a building supports the loan amount. That makes this valuation less flexible and more focused on risk control than market strategy.
Timing also matters. CMAs come early, before a home hits the market or before an offer goes in. Appraisals happen later, after a deal is under contract and financing is in motion.
Both require strong local knowledge, however. Data without such context leads to weak conclusions, no matter who prepares the report.
You can see the key differences between a CMA and an appraisal in the table below.
| Aspect | Comparative market analysis (CMA) | Professional appraisal |
|---|---|---|
| Who prepares it | Real estate agent | Licensed appraiser |
| Main purpose | Guide pricing or offer decisions | Protect lender and validate loan value |
| When it’s used | Before listing or making an offer | After offer acceptance |
| Level of formality | Informal and flexible | Formal and regulated |
| Property inspection | Usually none | Often full or drive-by inspection |
| Data focus | Recent local sales and competition | Sales data plus standardized valuation rules |
| Output | Price range | Single appraised value |
| Required by lenders | No | Yes |
When to perform CMA in real estate?
You perform a CMA when selling a home, making an offer, or responding to changes in the market. You should run it anytime a pricing decision matters. Timing shapes accuracy as much as data.
Before listing a home
This is the most common case. A fresh CMA sets a price that fits current demand. It helps avoid overpricing that stalls a listing or underpricing that leaves money behind.
Before making an offer
Buyers need a CMA to check whether an asking price makes sense. It grounds the offer in recent sales and local competition. That keeps decisions rational when emotions run high.
After a major market shift
Prices can move fast because of interest rate changes or sudden demand spikes. In such cases, you should always update a CMA.
When a listing sits too long
If a home isn’t getting traction, a new CMA helps diagnose the problem. It often reveals price resistance or stronger competition that didn’t exist at launch.
Before price adjustments or negotiations
Whether lowering a price or countering an offer, a CMA provides leverage. It replaces opinions with proof.
When is real estate appraisal worth it?
A home appraisal is worth it when an objective, lender-approved value is required. This usually happens once a deal moves past pricing strategy and into financing or legal territory:
- The most common case is a mortgage. Lenders order an appraisal to confirm the property supports the loan amount. Without it, the loan doesn’t move forward.
- Appraisals also matter during refinances. The appraised value affects loan terms, cash-out limits, and approval itself. Market opinions are not enough here.
- They’re useful in disputes and formal decisions too. Divorce settlements, estate planning, and tax appeals often require a documented, independent valuation. An appraisal carries legal weight that a CMA does not.
- Appraisals are typically required for unique or high-value properties as well. When comps are scarce or homes don’t follow local norms, a licensed appraiser adds credibility.
How to do a comparative market analysis for real estate? Steps & 6 tips
Getting a comparative market analysis for real estate requires a clear goal, defined selection rules, and pulling data manually from the MLS or through automation. The tips below show how to turn that foundation into a clear, usable process. Follow them to build a structured CMA and determine the value of your home with confidence.
1. Define the goal of the CMA
Start by deciding why you’re doing the CMA. The goal shapes every choice that follows, from data selection to final pricing:
- If you’re pricing a listing, the goal is market entry. You need to find the price range that attracts attention without leaving money on the table. Speed, competition, and buyer expectations matter most here.
- If you’re helping a buyer, the goal shifts to risk control. The CMA should answer one question: Does this price make sense based on what buyers actually paid nearby? In this case, recently sold properties carry more weight than active listings.
- If the CMA supports negotiation, the focus changes again. You’re looking for leverage. Price reductions, long days on market, failed listings, and weaker comps become valuable signals.
Be clear and specific before you pull numbers. A CMA without a defined purpose leads to vague conclusions.
2. Set clear selection rules
This step protects the CMA from bias and saves time later. Before you open the MLS, think about location, time, and property type:
- First, limit comps to the same neighborhood or a clearly defined area that buyers compare.
- Second, lock the time frame. Recent sales matter most. In stable markets, look back three to six months. In fast-moving markets, tighten that window.
- Next, define the property type. Don’t mix condos with single-family homes or compare townhomes to detached houses unless buyers truly treat them as substitutes.
- Then, set size and layout limits. A small range in square footage keeps comparisons honest.
- Finally, decide what not to include. Exclude distress sales, family transfers, or extreme flips if they don’t reflect normal buyer behavior.
Expert tip: Many practitioners look for comps that sold in the last 30–90 days and are within a tight radius (often up to ~5 miles) of the subject property.
3. Pull the data
You can pull required data manually from the MLS or use a dedicated CMA platform. Both methods work, but the numbers favor the latter.
30%
Agents who rely on advanced CMA tools complete sales cycles around 30% faster than those using fully manual workflows.
Source: realgeeks.com
What are the pros and cons of each approach?
- Manual MLS data pulls give you full control over comps and help you deeply understand the local market, but they are time-consuming and harder to scale. They also make it more difficult to present insights in a clear, client-friendly way.
- CMA platforms speed up data collection, standardize reports, and produce clean visuals that clients can quickly understand. The trade-off is cost and the risk of trusting auto-selected comps without review.
If you decide to partially automate your workflow, start by choosing the right CMA platform:
1. Begin with data quality. The tool should pull clean, current property records from reliable sources. Incomplete or outdated data will weaken your analysis from the start.
2. Review how the platform selects comps. Good tools rank properties by real similarity, not just by distance or price range. Better comp logic means less manual cleanup later.
3. Verify customization options. You should be able to remove weak comps, adjust values, and apply local context when the market doesn’t follow averages.
4. Finally, check the reports. They should be clear and easy to share with clients or partners. If the output needs heavy explanation, the tool adds friction instead of value.
👉 Check the differences between a client and a customer in real estate.
No matter how you pull the data—manually from the MLS or through a CMA platform—you still need to choose the right comps and apply sound adjustments. Tools can recommend them, but accuracy depends on applying the selection rules you defined earlier and validating every choice.
4. Read buyer behavior
A real estate CMA fails when it treats every sale as equal. Buyers don’t behave that way. Your job is to spot patterns, not prices in isolation. Answer one simple question: Where did buyers hesitate, and where did they move fast? This tells you more than the final sale price ever will.
| Signal | What it tells you | How to use it |
|---|---|---|
| Long days on market | Buyers noticed the listing but rejected the price | Set your price closer to recent closed sales, not active listings |
| Multiple price cuts | Seller chased the market | Use the final sale price instead of the original list price |
| Sale below list | Buyers had leverage | Price conservatively or negotiate harder |
| Fast pending status | Buyers competed | Price closer to the top of the range |
| Sale above list | Emotional or scarce market | Expect pushback if conditions change |
5. Set the value range
Your next move is to define a fair market value range for the property. Start by reading the spread your comps create. Review the low, middle, and high sale prices. Then flag any outliers. A sale driven by a cash buyer, a rushed timeline, or a short-term market spike can distort the picture. If it doesn’t reflect normal buyer behavior, set it aside.
Then, judge the quality of the range, not just its width. A tight range built on strong, recent comps signals higher confidence. A wide range often points to volatility, weak matches, or shifting demand. In those cases, caution beats optimism.
Once the range is clear, plan different pricing paths. This helps stress-test the value of the home being analyzed.
- Defensive strategy (lower half of the range): use in slower markets with high inventory.
- Balanced strategy (middle of the range): use when demand is stable, and comps are consistent.
- Aggressive strategy (upper half of the range, with a plan B): use only when supply is tight, and homes sell fast.
6. Generate a report
A CMA can be correct and still fail if the client can’t read it fast. Want to prepare a comparative market analysis that everyone will understand? Stick to this structure:
Page 1: The answer
- Property information
- Your recommended price range
- The “why” in three bullets (comp quality, market speed, competition)
- A clear next step (list price choice or offer plan)
Page 2: The comps snapshot
- Subject property overview
- Three to five best comps, with photos
- One short note per comp explaining why it matters
- A brief outlier note showing what you excluded and why
Page 3: Competition and adjustments
- Active listings within the same neighborhood
- Days-on-market trends
- Active competition count
- Key adjustments to the home being evaluated
Page 4: Housing market pulse and your logic
- Price cuts and list-to-sale behavior
- Market stance
- Final range and recommended strategy
To make your report easy to read, follow these dos and don’ts:
| Do | Don’t |
|---|---|
| Lead with the recommended range | Start with charts and raw tables |
| Use photos for every comp | Make the client imagine the property |
| Explain 2–3 key adjustments only | List 15 tiny tweaks nobody cares about |
| Call out exclusions (outliers) | Pretend every sale is equally valid |
| Use one page per idea | Dump everything into one long page |
Expert tip: Don’t just email the report—walk the client through it and leave them with a clean PDF.
Comparative market analysis—real estate template
Below you’ll find a free real estate comparative market analysis template. You can use it to organize and present your findings in a clear, client-friendly way. It helps you estimate the market value of a home by comparing it to similar homes in your area, using recent sales data.
What are best tools for comparative market analysis?
Some of the best tools for comparative market analysis include Cloud CMA, RPR, and market estimates from Redfin and Zillow. Each supports a different workflow, from polished client reports to quick market checks. What they have in common is efficiency:
~5
hours/week
Agents who use digital CMA tools save around five hours a week on average.
Source: realgeeks.com
Below, you’ll find a practical breakdown of the key tools for CMA, including their core features and pricing:
1. Cloud CMA (from Lone Wolf)
Cloud CMA is built for client-ready reports. It pulls in listing data, lets you build a clean CMA fast, and outputs a polished PDF or share link you can present in a listing appointment. It’s strong when you care about presentation (photos, simple charts, clear “here’s the range” storytelling) and want a repeatable workflow.
Cloud CMA pricing: Plans start at $49/month or $499/year, with a free trial available.
2. RPR (Realtors Property Resource)
RPR is a practical pick if you’re a Realtor (NAR member) and want a tool that covers both pricing and market context without extra spend. It combines a large property database with ready-made reports, market trends, and home value estimators, so you can answer client questions fast and generate shareable CMA-style outputs.
RPR pricing: The tool is included at no additional cost as an NAR member benefit.
3. Redfin/Zillow tools
Platforms like Redfin and Zillow are not full CMA platforms, but they offer accessible market data you can use to build your report manually. Both platforms show recent sales, price history, neighborhood trends, and basic comps—all without a paid subscription.
Redfin’s data tends to update faster in many markets because it pulls directly from brokerage feeds. Zillow’s “Zestimate” and sale history give a quick sense of value movement and how homes are priced relative to estimates. While neither replaces a professional CMA tool, these solutions are great for pre-work, quick checks, or prep before you dive into a deeper analysis.
Redfin/Zillow pricing: Free.
👉 Check out our real estate marketing automation guide.
What are limitations of comparative market analysis?
The main limitations of a CMA include data quality, fast-changing market conditions, and reliance on agent judgment. That’s why the report is used to estimate what a property is worth based on market behavior, not to deliver a final or legally binding number. What to keep in mind?
📊 Data quality
A CMA depends on finding a comparable home that is truly similar to the property in question. In many local real estate markets, especially smaller or unique ones, perfect matches don’t exist. Even homes within the same neighborhood can differ in layout, condition, or features, like a finished basement. When comps are weak, the CMA can vary more than expected.
⏱️ Market timing
The real estate market can shift quickly due to interest rates, inventory changes, or buyer sentiment. A CMA reflects conditions at a specific moment. If the market moves, the estimated value may lag behind reality. That’s why a CMA works best as a snapshot, not a long-term guarantee of what a home is worth.
🏠 On-site context
CMAs also don’t replace seeing the property in person. Photos and listing data can’t fully capture condition, layout flow, or functional issues. An experienced real estate agent with strong local market knowledge can spot details that raw data misses. That human judgment often makes the difference between a useful CMA and a misleading one.
📄 CMA vs appraisal
A CMA is not a formal valuation and isn’t accepted by lenders. It helps sellers set a price and lets buyers decide how to act, but it doesn’t carry the same weight as an appraisal ordered by a bank.
What is the cost of comparative market analysis in real estate?
The cost of a CMA is typically free when you’re working with an agent to buy or sell your home. Most experienced professionals offer a CMA free as part of the services they provide to help sellers set a listing price or advise buyers on what an offer should be.
In some cases, an agent may charge a nominal fee—often in the range of about $100 to $200. It can happen if you request a standalone CMA without entering into a listing agreement.
Key takeaways
A comparative market analysis is a valuable tool that supports accurate pricing decisions. When done right, it turns recent sales, active competition, and local market signals into a clear value range you can act on.
As a real estate agent, you should offer a CMA as part of your services. As a real estate agent, you should offer a CMA as part of your services. Promote it alongside your listings on a website built with Placester. Let clients get a CMA and see comps similar to the home in question. This builds trust faster and positions you as the expert guiding the decision.
AI Websites for Real Estate
Get a custom, ready-to-edit website
in less than 4 minutes.
FAQ
Should you order a professional CMA or do it yourself?
When you’re buying or selling, a professional CMA prepared by an experienced agent is usually the better choice. It combines current data with local market knowledge and on-the-ground insight you won’t get from raw numbers alone. A DIY CMA can work for early research, but it carries more risk when money is on the line.
What do you need to create accurate CMA?
To produce a CMA, you need high-quality comparable sales and an understanding of local market conditions. Access to MLS data helps, but accuracy depends on how well you choose and adjust comps. Seeing the property in person and knowing the neighborhood fills gaps that numbers alone miss.
What mistakes to avoid while creating comparative market analysis?
Avoid using outdated sales, weak comps, or asking prices instead of closed deals. Don’t over-adjust to force a desired number. Ignoring buyer behavior or current competition often leads to pricing that the market rejects.
How often should CMA be updated in a changing market?
In a fast-moving market, update a CMA every few weeks or after any major shift. Even in stable conditions, you should always refresh a CMA before listing, repricing, or renegotiating.
Published on

Take your real estate website to the next level with Placester!
Discover new opportunities and save thousands of dollars every year.